← Partner Events
    In-person partner eventColts Neck, NJ

    Understanding Today's Market
    & Communicating It With Confidence

    An Educational Networking Experience for Real Estate Agents, Attorneys, and Business Professionals

    Two perspectives. One shared conversation. Abdel Khawatmi brings the mortgage and housing view; Justin Lotano brings the financial planning and wealth management view. Together, we'll break down what's moving the market and how to talk about it with your clients in plain English.

    Save the date. Come for the conversation, stay for the connections.

    Co-host

    Got Mortgages

    Powered by PRMG · NMLS #75243

    Co-host

    Shorepoint Wealth Management

    Financial planning & wealth management

    • Education
    • Communication
    • Technology
    • Relationships

    Inside the room

    What you'll walk away with.

    This is an educational discussion, not a sales pitch. The goal isn't just to fill a room. It's to bring the right people together, provide real value, and build relationships that last long after the event.

    • The five-signal market model: economy, inventory, pricing, financing and communication, and how to connect the dots between them.
    • Why the Fed headline isn't the whole story, and how bond markets and mortgage-backed securities shape mortgage pricing.
    • How holistic financial planning looks at the same market through cash flow, retirement and life transitions.
    • A simple, repeatable weekly market briefing and a quick client-ready report you can use without becoming an economist.
    • How to use video, email and AI to turn one verified insight into consistent, useful client communication.

    The conversation

    Four topics. Two perspectives.

    The evening follows four pillars from the event flyer. The outline below is a guide to the discussion, not a script or exact timing.

    1. 01

      Market Education

      Simplifying inflation, interest rates, the 10-year Treasury, bond markets and economic trends.

    2. 02

      Practical Communication

      Turning complex market conditions into relevant client conversations.

    3. 03

      Technology & AI

      Using email, social and modern tools to communicate insights efficiently and authentically.

    4. 04

      Relationship Building

      Creating value through education, not sales pitches.

    Market basics primer

    Market basics, in plain English

    What is inflation, and why does everyone keep talking about it?

    Inflation is the general rise in prices over time, which means a dollar buys a little less than it used to. It matters because it shapes how the Federal Reserve sets policy, how investors price bonds and how families feel about their budgets. When you explain it to a client, connect it to what they actually experience: groceries, insurance, rent and the cost of the things they're planning for.

    What does the Federal Reserve control, and what doesn't it?

    The Fed sets a short-term policy rate and influences the economy through its decisions and its communication. It does not directly set mortgage rates or the return on any investment. Longer-term borrowing costs are shaped by the bond market, which reacts to inflation, economic data and expectations about the future.

    Why does the 10-year Treasury get so much attention?

    The 10-year Treasury is a widely watched benchmark for longer-term borrowing costs. Mortgage pricing tends to move with the broader bond market, and the 10-year is a convenient way to see the direction of that market. It's a signal, not a formula: many other factors affect what any one borrower is offered.

    How do bond prices and yields relate?

    They move in opposite directions. When demand for bonds rises, prices go up and yields go down; when demand falls, prices drop and yields rise. That relationship is why strong economic news or inflation surprises can ripple through mortgage pricing and investment portfolios on the same day.

    How should we talk about economic trends without predicting the future?

    Nobody can promise where the market goes next, and clients trust you more when you don't pretend to. Explain what's happening, why it matters to their goals and what decisions are within their control. Then point them to the right professional for their specific situation.

    Got Mortgages perspective

    Abdel's Market Intelligence: Five signals. One market story.

    Talking points prepared from Abdel's Market Intelligence presentation for this event. The current national and local figures are shared live in the room and are not repeated here; this page keeps the framework so you can apply it with fresh, dated data each week.

    The job is not to predict every data point. The job is to connect the dots.
    1. 01

      Economy

      Inflation + jobs. The backdrop that sets the tone for everything else.

    2. 02

      Inventory

      Supply + demand. How many homes are available compared with how many buyers want them.

    3. 03

      Pricing

      Sold + asking. What homes actually sell for, not just what they're listed at.

    4. 04

      Financing

      Rates + programs. The cost and the menu of options available to a buyer.

    5. 05

      Communication

      Meaning + action. What it all means for this client, and the next step.

    Connecting the dots

    The economy is still setting the tone

    Inflation and employment often pull in different directions. Sticky prices can keep longer-term yields elevated, and slower inflation doesn't mean prices go back down. A resilient job market can support buyers, while a sharp slowdown may ease yields but weaken demand and qualification. Different indicators come out on different dates, so don't treat them as one number. And a lower mortgage rate is not automatically the sign of a healthier economy.

    The Fed does not set your mortgage rate

    Mortgage pricing responds to the bond market and mortgage-backed securities. Think of it as a chain: economic data (inflation and jobs) moves Treasury yields (growth and policy outlook), which moves mortgage-backed securities pricing (spread and prepayment risk), which shows up in loan pricing (lock timing and borrower factors). Watch bonds and mortgage-backed securities, not just a Fed headline.

    Plan for scenarios, not a single guess

    Scenario planning is more useful than guessing one number. If inflation eases, rates could moderate and buyers may return faster than new inventory appears. If rates stay high, pricing accuracy, cash-to-close planning and concessions become more important. If employment weakens, lower yields may arrive alongside fewer qualified buyers and more uncertainty. The strategy changes with the reason the market moves.

    Zoom out, then zoom in locally

    Look at long-term appreciation before reacting to one month. A repeat-sales price index is not the same as the median price of homes sold, and the state and the Shore are not one price point. Whether homes sell above, at or below asking is a strong signal of negotiating power, and the same state can contain two different markets. County averages set context; town, condition and price point determine leverage. One median can never replace town-level comps and property-level analysis.

    The financing menu is bigger than one rate

    Start with the borrower's goal, then choose the right program family. Some borrowers fit standard documentation; self-employed and commission-based clients may be evaluated with alternative documentation, which still requires full underwriting. Community lending programs may help eligible households with cash to close, so ask whether a buyer qualifies before assuming the down payment is the obstacle. Price reductions and seller concessions solve different problems, and no short-term payment strategy should ever be presented as a promised future refinance. Every option depends on eligibility, program rules and review.

    Communicating it with confidence

    Your weekly market briefing

    1. 01

      Price

      Median and trend

    2. 02

      Supply

      Active and new listings

    3. 03

      Speed

      How quickly homes are selling

    4. 04

      Leverage

      Above, at or below asking

    5. 05

      Options

      Rates and programs, from your lender partner

    One useful fact can fuel a week of content

    1. 1

      Hook

      Ask the question clients are already asking, like 'Are sellers finally negotiating?'

    2. 2

      Data

      Share one verified local figure, with its date and source.

    3. 3

      Meaning

      Explain what it means for a buyer or seller.

    4. 4

      CTA

      Invite a specific question or conversation.

    Record one short video, then share it across Reels, Shorts, LinkedIn and email. The agent who explains wins more attention than the agent who reposts headlines.

    AI is the analyst. You are the advisor.

    1. Input

      Town, date and verified facts

    2. Draft

      Video script, email, FAQ or blog

    3. Review

      Verify the math and compliance

    4. Send

      A client-specific next step

    Try this prompt

    Explain these verified local numbers to a first-time buyer in a short paragraph. No predictions; include one next step.

    Shorepoint Wealth Management perspective

    The Planning Lens: One plan. Every piece connected.

    General education drawn from Shorepoint Wealth Management's published planning approach and Justin Lotano's public professional background. It is not investment, tax or legal advice, and Justin's own examples are reserved for the live discussion.

    Start with the goals. Then build the plan around them.
    1. 01

      Cash Flow

      What comes in, what goes out and what's left to put toward goals.

    2. 02

      Investments

      Strategies aligned with a client's goals, timeline and comfort level.

    3. 03

      Retirement

      Planning for income designed to last, with the right balance of flexibility and control.

    4. 04

      Tax & Estate

      Tax and estate considerations treated as part of the whole picture, not an afterthought.

    5. 05

      Life Transitions

      Divorce, retirement and family changes that reshape priorities and timelines.

    Connecting the dots on the planning side

    A holistic plan is a roadmap, not a product

    Shorepoint describes a financial plan as a roadmap that brings every part of a client's financial life into one personalized strategy, from cash flow management and investment strategies to retirement planning, tax optimization and estate planning. The plan is meant to adapt as life evolves, balancing immediate needs with long-term goals.

    Three steps: discover, research, implement

    Shorepoint's process starts with a discovery session where the client does the talking and the advisor listens and asks questions to understand what they want to pursue. Next comes review and research, looking at different approaches before presenting a plan. Implementation happens only with the client's permission.

    Why inflation matters in a long-term plan

    Inflation erodes purchasing power over time, and retirement can span decades. That's why the same economic signal Abdel watches for mortgage pricing also matters in planning conversations about income, spending and how a plan holds up over the long run. A plan isn't set once; it's revisited as conditions and goals change.

    The questions behind retirement planning

    Retirement conversations often come down to a few questions: How do I create income that lasts? How much flexibility and control do I want to keep? How do I balance growth with stability? There's no single answer, which is why planning starts with the individual's goals and circumstances.

    Divorce is a financial event, too

    As a Certified Divorce Financial Analyst (CDFA®), Justin focuses on the long-term financial implications of divorce settlements. Through Shorepoint Divorce Solutions, he helps clients gather and organize financial documents, work through New Jersey's Case Information Statement, evaluate settlement options with real-world clarity, understand post-divorce cash flow and affordability, and make informed decisions about housing and mortgage strategy. A CDFA professional handles the detailed financial analysis so attorneys can focus on the legal issues; it is not a substitute for legal advice.

    Communicating it with confidence

    Planning conversation checklist

    1. 01

      Listen

      Let the client do the talking first.

    2. 02

      Goals

      Name what they want to pursue and by when.

    3. 03

      Picture

      Organize the full financial picture, including the home.

    4. 04

      Options

      Review approaches before recommending one.

    5. 05

      Revisit

      Keep the plan current as life changes.

    The hosts

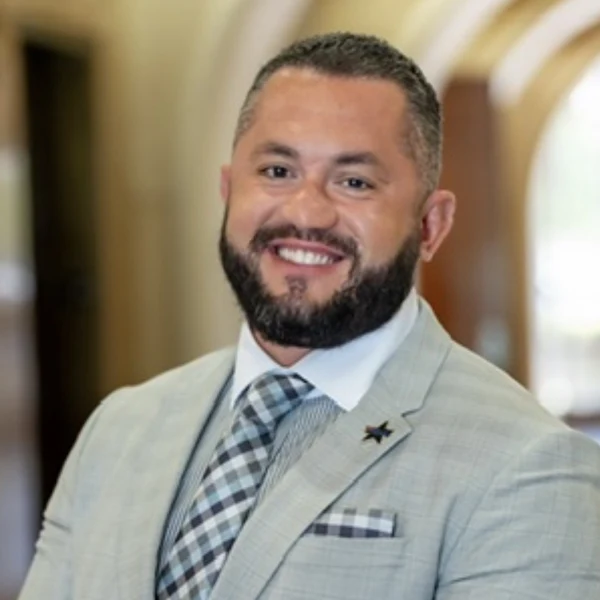
    Abdel Khawatmi headshot

    Co-host · Speaker

    Abdel Khawatmi

    Got Mortgages · Powered by PRMG

    About

    Got Mortgages is an AI-powered partnership platform and mortgage team, powered by Paramount Residential Mortgage Group, Inc. (PRMG), NMLS #75243. The team brings lending strategy together with referral partner education, practical technology and ongoing client relationships.

    Perspective

    Abdel brings the mortgage and housing view through his Market Intelligence framework: five signals that tell one market story. His focus is helping professionals connect the dots between the economy, inventory, pricing, financing and the conversation with the client, without predicting every data point.

    Explore our partner approach
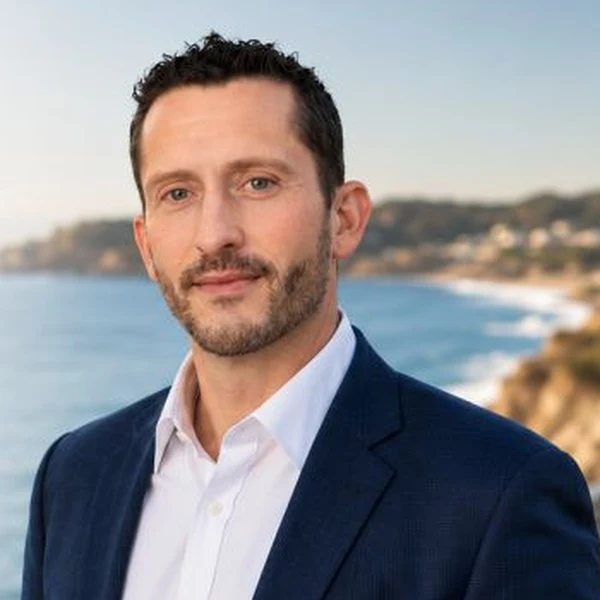
    Justin Lotano headshot

    Co-host · Speaker

    Justin Lotano, CDFA®, CRPC

    President · Shorepoint Wealth Management

    About

    Justin is the President of Shorepoint Wealth Management in Colts Neck, New Jersey, and has worked in the financial services industry since 2006. Before launching Shorepoint in 2025, he spent roughly a decade with Wells Fargo Advisors in Red Bank, most recently as a Managing Director with Wells Fargo Advisors Financial Network.

    He has been a Certified Divorce Financial Analyst (CDFA®) for more than a decade and also founded Shorepoint Divorce Solutions, helping people navigate the financial side of divorce with clarity and structure. Justin earned a Bachelor's degree in Business Management from Loyola University Maryland, serves as President of the Colts Neck Lions Club and is involved with the Association of the U.S. Army, HABcore and Covenant House.

    Perspective

    Justin brings the financial planning view: how the same market shows up in cash flow, retirement and long-term planning, and how major life transitions such as divorce change the picture. Shorepoint describes its approach as comprehensive, holistic planning built around a three-step process: a discovery session where the client does the talking, review and research, and implementation with the client's permission.

    Visit Shorepoint Wealth ManagementShorepoint Divorce Solutions

    Two perspectives, one client

    Where the signals meet the plan.

    Abdel's five signals and Shorepoint's planning lens look at the same client from two sides. These are general talking points prepared for the evening, not statements from either speaker or advice for any individual situation.

    Market signalEconomy
    Planning question

    How does inflation affect purchasing power and the long-term plan?

    Market signalInventory
    Planning question

    Does the timing of a move fit the client's broader goals and timeline?

    Market signalPricing
    Planning question

    How does the home fit within the client's overall financial picture?

    Market signalFinancing
    Planning question

    What does the payment mean for monthly cash flow and other goals?

    Market signalCommunication
    Planning question

    Are the lender, planner, agent and attorney working from the same plan, with the client's permission?

    Education first. Relationships always.

    Communicate it with confidence

    Turn market news into a client conversation.

    1. 01

      Translate

      Pick one headline your clients are hearing. Explain what it is in one or two plain sentences.

    2. 02

      Relate

      Connect it to a real decision: buying, selling, refinancing, retiring or planning through a life change. Skip the jargon.

    3. 03

      Refer

      Point them to the right professional for their specific situation. You don't have to have every answer; you do have to know who to call.

    Technology & AI, used responsibly

    • Draft educational emails and posts faster, then fact-check and rewrite them in your own voice.
    • Keep private client information out of public AI tools.
    • Share consistent, useful insights instead of a flood of generic content.
    • Measure conversations and follow-through, not just how much you posted.

    Proof, not just talk

    We don't just talk about it. We execute.

    Everything we're covering tonight is something both teams already do: market updates, local education and planning content, published where clients can actually read it. Here's a sample of what's live right now. Each link opens on that team's own website in a new tab.

    Got Mortgages

    Abdel's team publishes weekly market updates, local blogs and market insights at GotMortgages.com.

    Shorepoint Wealth Management

    Justin publishes planning and divorce-finance education on Shorepoint's websites and shares a weekly market commentary with clients.

    Who should attend

    • Real estate agents
    • Family law and estate attorneys
    • Financial and business professionals
    • Referral partners who want a clearer way to explain the market to clients

    Educational discussion only. Nothing on this page is a loan offer, investment advice or a recommendation for any individual. Financing is subject to individual eligibility, program requirements and review. Ask each professional about your specific situation.

    Market education & event FAQs

    How do stocks connect to housing and the broader economy?

    A stock represents ownership in a company. Stock prices reflect changing expectations about business conditions, earnings and risk; housing and bond markets respond to some of the same economic news, but they do not move in lockstep. A stock-market headline is context, not a signal that someone should buy a home or change an investment.

    What is the difference between stocks and bonds?

    Stocks represent ownership; bonds represent lending to an issuer. Each carries risks, and each can play a different role in a financial plan. Explain the concepts rather than choosing investments for a client. A financial planning professional can consider how those choices fit the person's goals and circumstances.

    How is financial education different from financial advice?

    Education explains concepts such as purchasing power, cash flow, diversification and risk. Individual financial advice considers a person's full circumstances before recommending an action. An agent can explain a headline in plain English and refer planning questions to an appropriately qualified professional; avoid telling a client which stock to buy, sell or hold.

    How can I discuss diversification without recommending investments?

    Diversification means spreading exposure across different investments rather than relying on one company or market. It can reduce concentration risk, but it does not remove risk. Keep the conversation about the concept; the appropriate mix depends on the client's goals, timeline and ability to handle uncertainty.

    How do I explain a headline without making a prediction?

    Separate the verified fact from the interpretation. Name the source and reporting date, explain the concept and connect it to a question the client can control. Avoid saying what prices or markets will do next. Review every AI draft for factual accuracy and your professional boundaries before sharing it.

    How can AskGotMortgages help with client communication?

    Prepare a prompt from a general market headline using the tool below, copy it and paste it into AskGotMortgages.com. Ask for educational mortgage and housing context, not investment recommendations. Review the response yourself; stock selection and individual financial planning questions belong with a qualified financial professional.

    When and where is the event?

    Thursday, November 12, 2026, from 5:00 PM to 7:00 PM Eastern Time at Source Brewing, 300 NJ-34, Colts Neck, NJ.

    Who is hosting?

    Abdel Khawatmi of Got Mortgages, powered by PRMG, and Justin Lotano of Shorepoint Wealth Management.

    Who is this for?

    Real estate agents, attorneys and business professionals who want a clearer understanding of today's market and a better way to communicate it to their clients.

    What's the format?

    An in-person educational discussion followed by networking. It's education, not a sales pitch.

    Can I ask about a specific client situation?

    Keep questions general and leave out names and private financial details. Individual mortgage, financial planning, legal or tax questions need a one-on-one conversation with the right professional.

    How do I connect with the hosts after the event?

    Book a strategy call with Abdel through the button on this page, or visit Shorepoint Wealth Management's website to reach Justin's team.
    AskGotMortgages

    A clearer client conversation starts here.

    General headlines only; leave out names and private client details.

    Event materials

    Understanding Today's Market workbook

    Original presentation from November 12, 2026, presented by Abdel Khawatmi. The PDF includes dated market figures and financing examples; verify current sources and program details before reusing them. The educational page above stays concept-only.

    Download event workbook

    Bring your questions to the table.

    Got Mortgages, powered by PRMG. Shorepoint Wealth Management. Two perspectives on today's market, one shared commitment to education and lasting relationships.

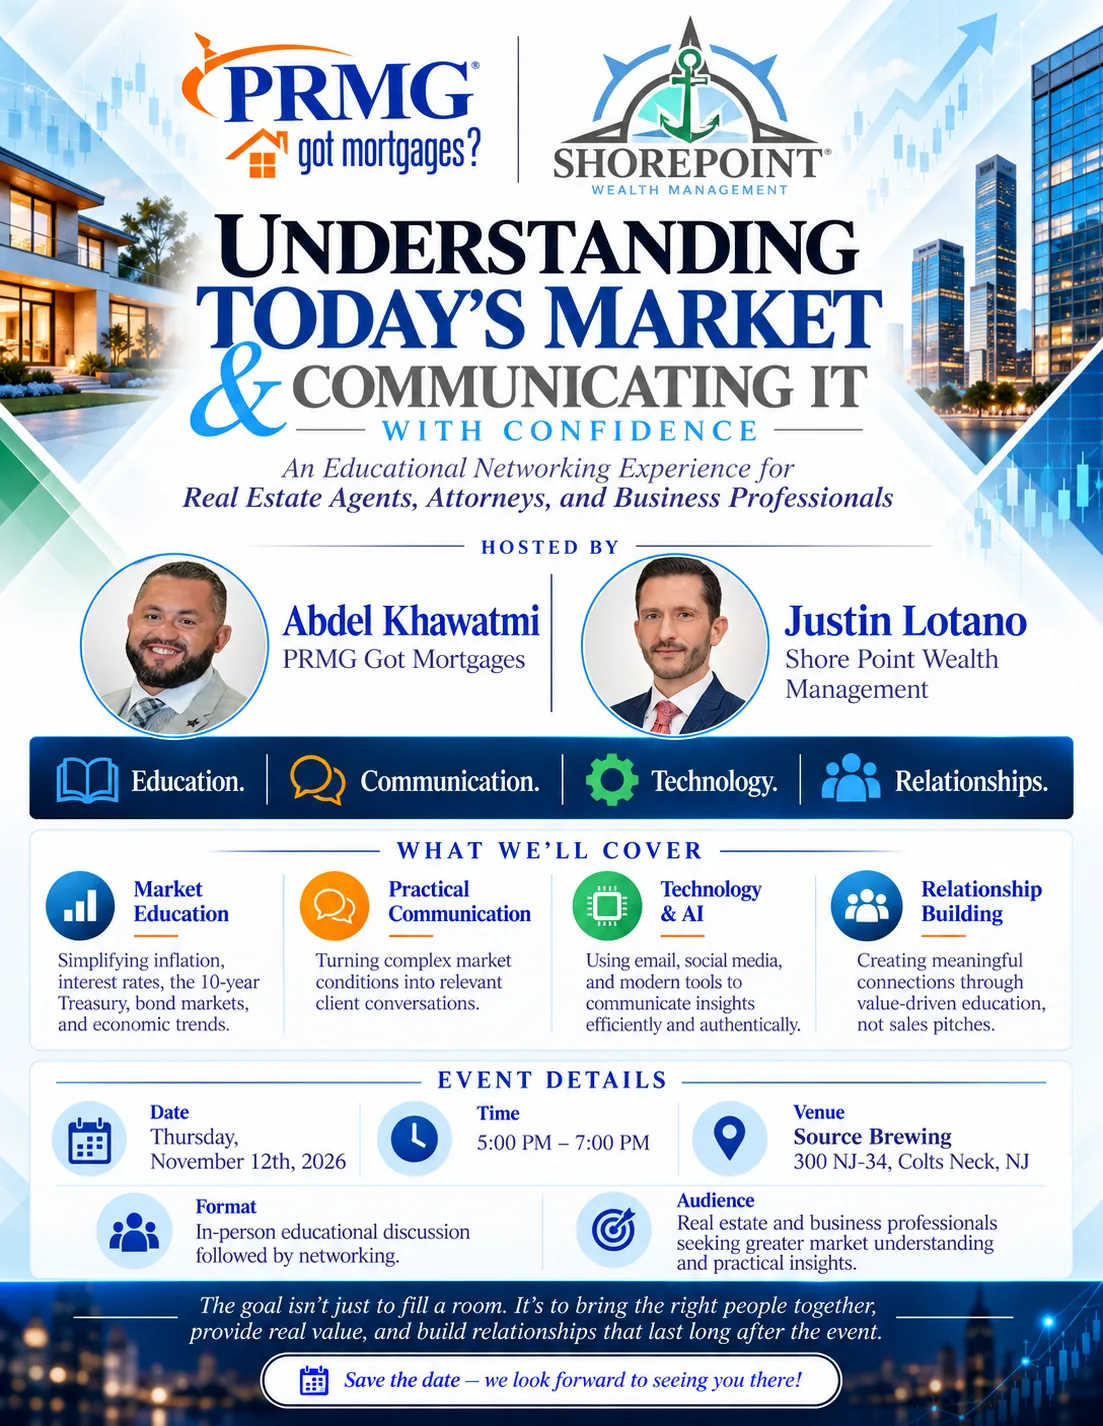
    Understanding Today's Market & Communicating It With Confidence event flyer: Thursday, November 12, 2026, 5:00 PM to 7:00 PM at Source Brewing, 300 NJ-34, Colts Neck, NJ, hosted by Abdel Khawatmi of PRMG Got Mortgages and Justin Lotano of Shorepoint Wealth Management

    We use strictly necessary storage to run this site. With your permission we also load optional tools, like our scheduling calendar and office maps, from third parties. See our Cookie Policy and Privacy Policy.