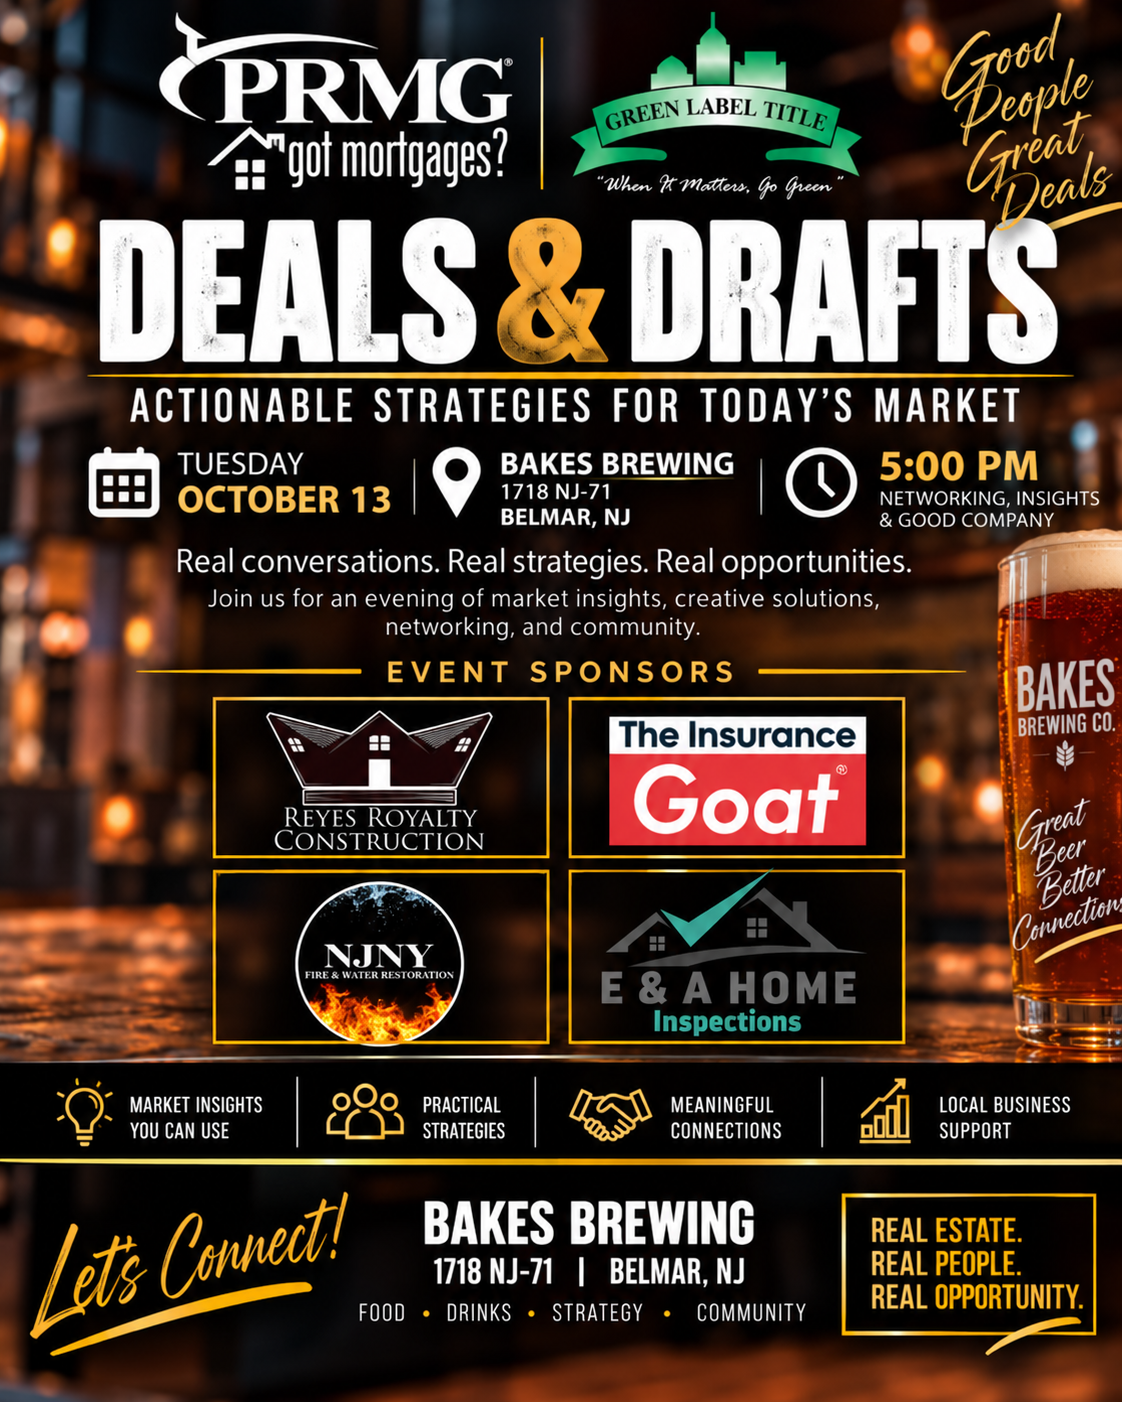
Held October 13, 2026 at Bakes Brewing in Belmar with Abdel Khawatmi of PRMG Got Mortgages and Steve Green of Green Label Title: an evening of local market data, creative financing solutions, networking and community.
Hosted by Got Mortgages, Powered by PRMG, and Green Label Title.
Event Recap
The Event. The Takeaways.
On October 13, 2026 at Bakes Brewing in Belmar, Abdel Khawatmi of PRMG Got Mortgages and Steve Green of Green Label Title worked through today's market, title and closing operations, strategic financing and practical AI execution with local real estate professionals.
Watch the replay, grab the materials below, then work the recap checklist one topic at a time.
Start with the corrected recap and action checklist, then keep the full presentation, infographic, sponsor showcase and brand audit flyer together.
PDF
Event Recap & Action Checklist (PDF)
The nine-page edited recap: title readiness, market context, underwriting updates, seller credits, the 2/1 example, alternative financing, AI and next steps.
PDF
Deals & Drafts Presentation
The full presentation from the Deals & Drafts session at Bakes Brewing.
PNG
Deals & Drafts Infographic
One page: the deal before the deal and the drivers behind mortgage rates. Great to share with clients and partners.
PNG
Event Sponsor Showcase
Every sponsor at a glance: services, phone, email, website and address. Share it with your clients and partners.
PDF
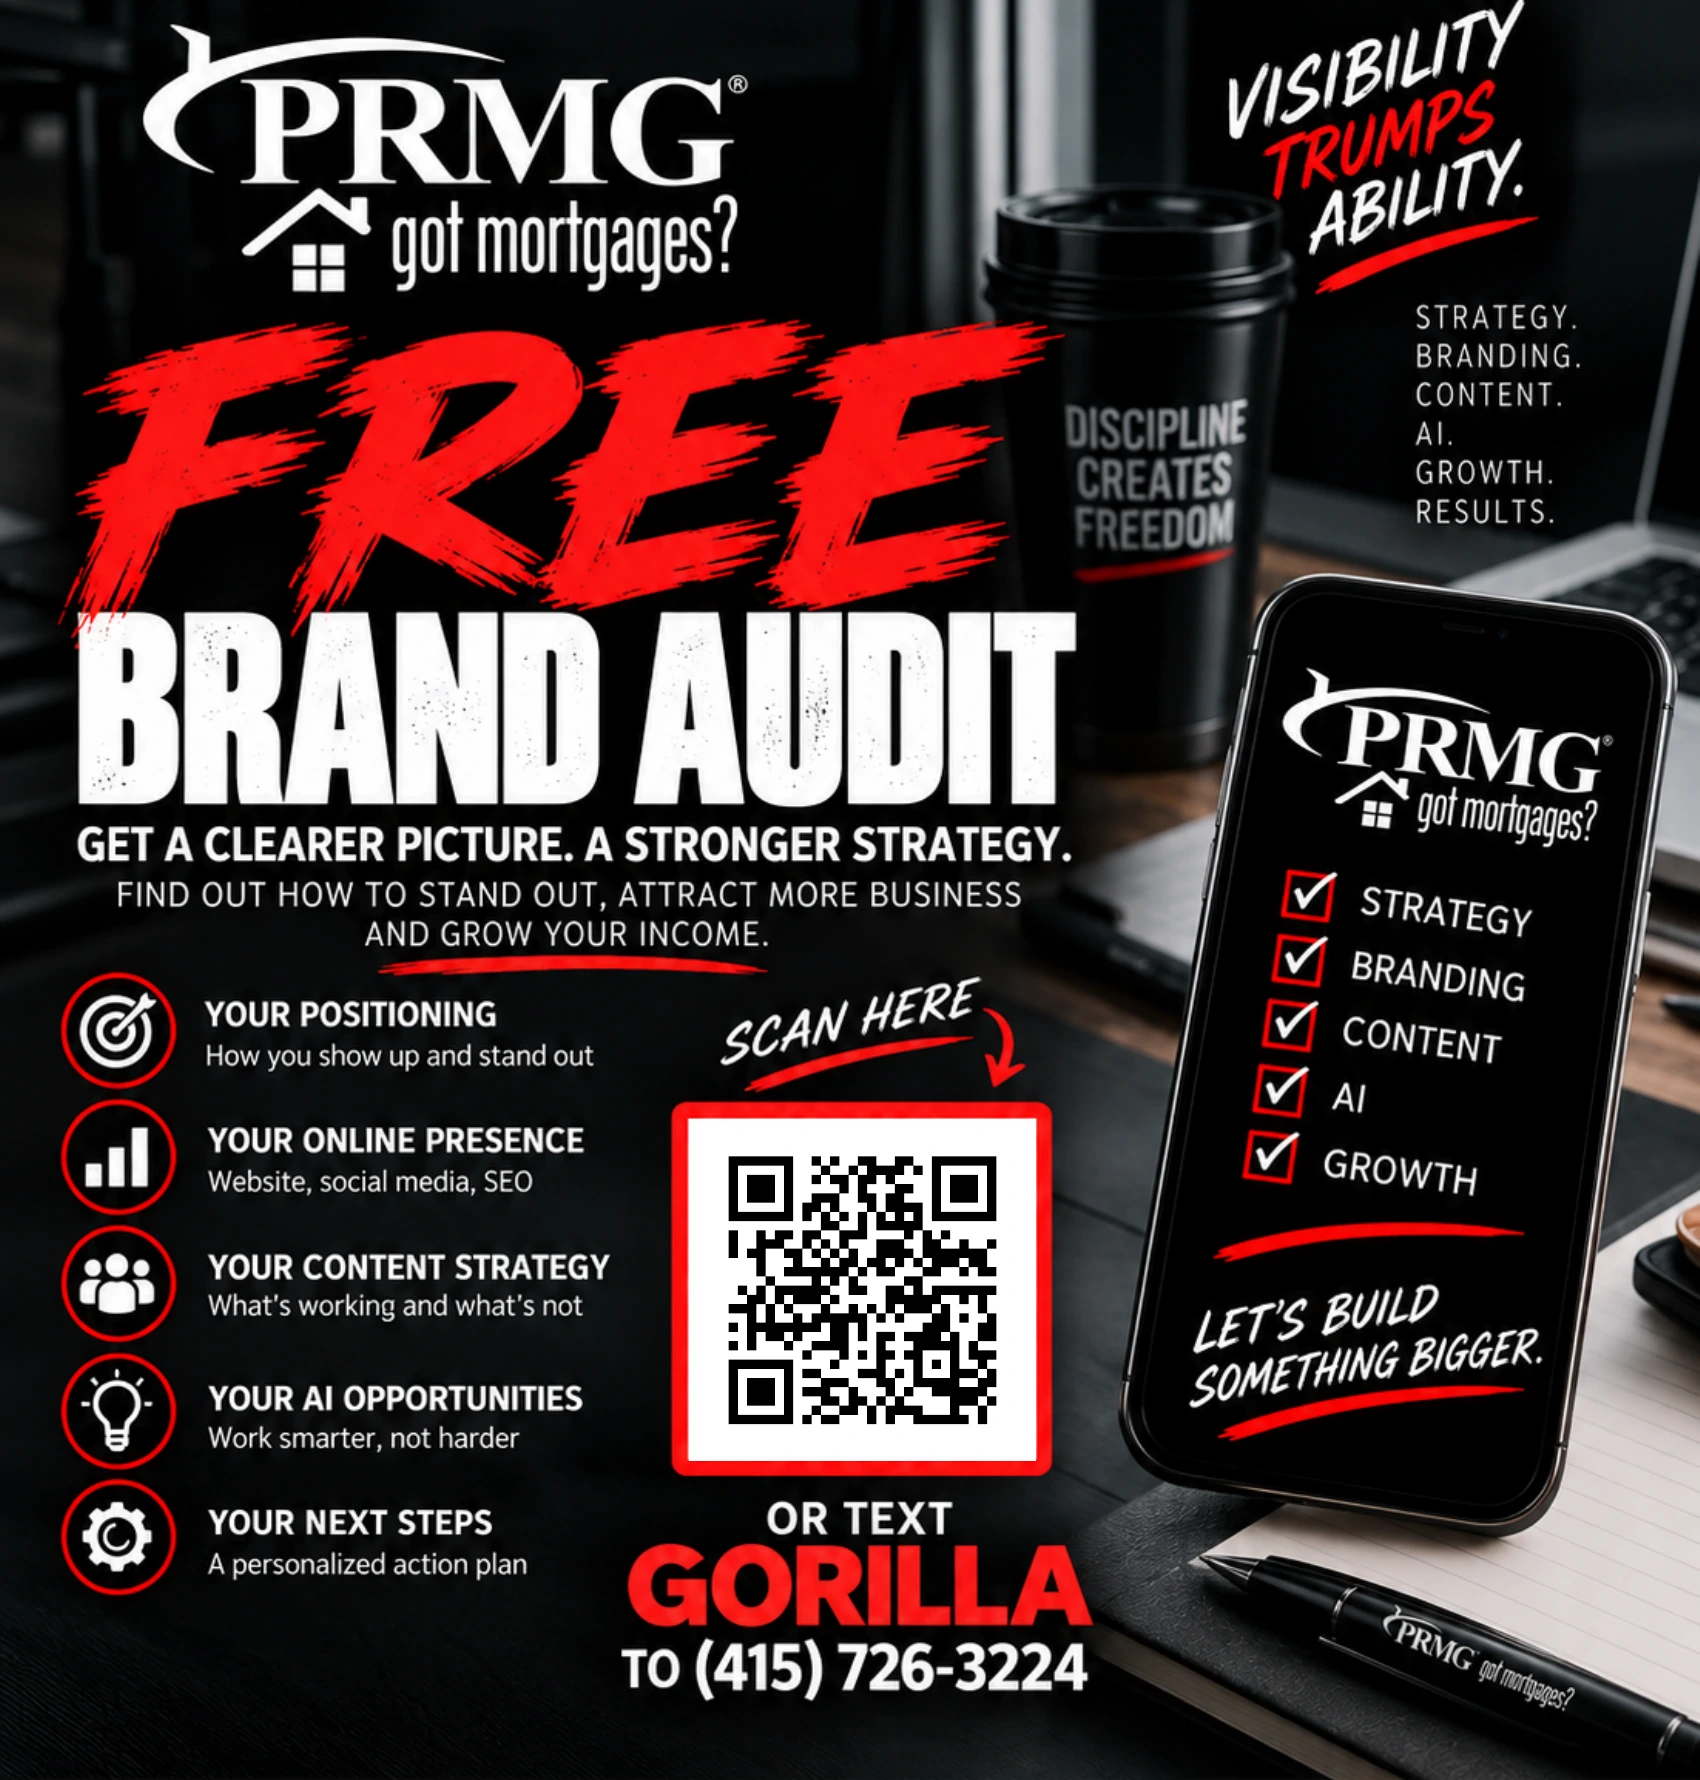
Free Brand Audit
The brand audit flyer: positioning, online presence, content strategy, AI opportunities and your next steps.
Event Recap Checklist
Put the Night to Work.
The recap, organized by topic. Tick each item as you apply it; your ticks are saved in this browser only. Policy notes checked October 20, 2026. This organizes the event recap into a working checklist; it is not a verbatim transcript.
0 of 45
Partners and title
Title and closing readiness
0 of 5 done
Summarized from the host-provided briefing. Operational observations are speaker perspectives, not findings about all title companies.
A coordinated professional network
Partner
Contribution discussed
Green Label Title / Steve Green
Title coordination, communication and closing preparation.
The Insurance Goat
Responsive insurance guidance and quotes that support closing timelines.
Reyes Royalty Construction
Renovation, repair and construction planning, including renovation-loan projects.
E & A Home Inspections
Clear inspection reporting and client education.
NJNY Fire & Water Restoration
Fire, water and property-damage restoration support.
Steve Green emphasized business leadership, modern systems and a supported team as ways to reduce friction. The practical lesson: complete information and clear ownership reduce avoidable rework.
Market education
Rate drivers and the local market
0 of 6 done
Historical event discussion, not a current market report. Figures were shared in the event materials and have not been independently audited.
Monmouth and Ocean County snapshot (event-reported)
Measure
Monmouth
Ocean
Homes sold, trailing 12 months
11,981
11,936
Year-over-year unit change
-10.9%
-11.3%
Average sale-to-list ratio
99.0%
97.9%
Median sale-to-list ratio
~100.0%
98.7%
Historical presentation figures only. Confirm the source, property types, reporting window and geography before reusing them with a client.
Underwriting
The four Cs and changing rules
0 of 7 done
Credit (profile and payment history), Collateral (property, project eligibility and condition), Capital (down payment, eligible assets and reserves) and Capacity (ability to repay and qualifying income). Lender overlays and transaction-specific requirements still apply. Sources [1] [2], checked October 20, 2026.
Closing guarantees and 7 to 14 day timelines discussed at the event require separate written terms and file-specific confirmation.
Financing strategy
Where should the seller credit go?
0 of 4 done
Illustrative education, not a rate quote or commitment to lend. Sources [3] [4] [5] [6], checked October 20, 2026.
Seller contribution reference
Program / scenario
Typical maximum / basis
Conventional primary or second home, LTV/CLTV above 90%
3%
Conventional primary or second home, 75.01% to 90%
6%
Conventional primary or second home, 75% or less
9%
Conventional investment property
2%
FHA
6% of sales price, subject to eligible costs
USDA guaranteed
6% of sales price, subject to eligible costs
VA
4% of reasonable value for defined concessions; ordinary closing-cost credits are treated separately
Conventional percentages use the lower of sales price or appraised value. Contributions are limited by eligible actual costs and program rules. Seller credits do not replace a required down payment or reserves.
Payment example
A 2/1 buydown, explained
0 of 5 done
Illustration: $450,000 loan, 30-year fixed, 7.25% note rate. Principal and interest only; taxes, insurance, mortgage insurance, HOA fees and closing costs excluded. Sources [7], checked October 20, 2026.
2/1 buydown payment path
Period
Payment basis
Buyer pays
Subsidy / mo.
Year 1
5.25%
$2,484.92
$584.88
Year 2
6.25%
$2,770.73
$299.07
Years 3 to 30
7.25%
$3,069.79
$0.00
Total illustrative subsidy for the first 24 payments: $10,607.31. The lender still receives the full scheduled payment of $3,069.79 each month; the funded subsidy covers the difference in years one and two.
The complete buyer conversation compares the monthly payment, cash needed at closing, cash remaining afterward and total borrowing cost. Figures are calculations from the stated assumptions, not advertised loan terms.
Alternative financing
A different way to document
0 of 8 done
Products discussed at the event. These examples are not a current lender rate sheet or product matrix, and they are not automatic approvals.
AI and visibility
Practical systems, measurable work
0 of 6 done
Event examples and internal business figures. Overall business results do not isolate the effect of AI.
Reported business results
Internal measure
Reported result / period
Units & Volume
+72%, January through September 2026
Profitability
+56 BPS, January through September 2026
Units
+104%, Two-year growth as of June 2026
Volume
+64%, Two-year growth as of June 2026
Source: internal business figures shared by Abdel Khawatmi. Overall results; AI's individual contribution has not been measured. Reporting periods overlap.
Next steps
From recap to action
0 of 4 done
Use this as a working checklist with your clients and referral partners.
Source notes and policy references (checked October 20, 2026)
Educational material only, not a commitment to lend. It does not replace the current agency guide, lender matrix, Loan Estimate or professional advice. All loans are subject to credit, property and program approval. Abdel Khawatmi, NMLS 1712023 · PRMG NMLS 75243 · Equal Housing Opportunity.
The team behind the deal
Partners & Sponsors
Every closing takes a team. These are the local pros who help your clients get to the table and protect the home after.
Host partner
Green Label Title
"When It Matters, Go Green"
What they do
Title search, title insurance and settlement services for buyers, sellers and lenders.
How they help
A clear seven-step process, from open order to post-closing, so issues surface before closing day, not on it.
Why it matters
Paired with a prepared financing file, deals close on time with fewer last-minute fires.
Host partner
Got Mortgages
Powered by PRMG
What they do
Residential mortgage lending and financing strategy for buyers, homeowners and investors.
How they help
Structure the deal before the deal: concessions, buydowns and preapprovals that make offers stronger.
Why it matters
AI prepares, a licensed loan officer advises, so partners get fast answers and clients get real guidance.
Construction
Reyes Royalty Construction
Residential construction, renovation and repair work.
How they help: Turns fixer-uppers and inspection findings into realistic scopes, so buyers see the potential and deals keep moving.
Insurance
The Insurance Goat
Homeowners and property insurance guidance.
How they help: Fast, accurate quotes that feed the real monthly payment and keep insurance from delaying the closing.
Restoration
NJNY Fire & Water Restoration
Fire, water and damage restoration across NJ and NY.
How they help: Responds when damage hits a listing or a new home, protecting value for owners and buyers alike.
Home inspection
E & A Home Inspections
Professional home inspections for buyers and sellers.
How they help: Clear, timely reports that give buyers confidence and agents the facts to negotiate.
01 · The process
The Deal Before the Deal
Preparation creates opportunity. Financing strategy starts here, not after the contract.
Step 1
Buyer
Consult
Start with goals, timeline and comfort payment before a single showing.
Step 2
Docs
Reviewed
Income, assets and credit are reviewed up front, not after the contract.
Step 3
Budget
Strategy
Set a payment-based budget and a plan for concessions before writing offers.
Step 4
Offer
Confidence
Write with a financing story the listing agent can trust.
Step 5
Accepted
Execute
A prepared file moves to clear-to-close with fewer surprises.
02 · Seller concessions
$15,000. What Does This Buyer Need?
Same dollars. Different job. Choose the strategy around the buyer's cash, payment and time horizon.
2/1 Buydown
Relief now
Subsidizes the first 24 monthly payments. The full payment follows.
Discount points
Lower rate
Pays upfront for a lower note rate. Compare the break-even.
Closing costs
Keep more cash
Covers eligible costs due at closing and preserves buyer funds.
Price reduction
Lower price
Reduces the contract price and loan at the same LTV. Negotiate separately.
The best use depends on the buyer.
Seller credits must fit loan-program limits and eligible costs. A price reduction is an alternative negotiation, not a use of closing credit.
In this seller-funded example, about $10,607 funds the payment subsidy upfront.
The buyer qualifies at the full 7.25% note rate. Budget for the full payment after year 2.
The fund covers the gap. The note rate stays fixed. Refinancing is not guaranteed.
Illustrative example; amounts rounded. P&I excludes taxes, insurance and MI. Source: Fannie Mae Selling Guide B2-1.4-04.
$2,485
Year 1 · 5.25%
$2,771
Year 2 · 6.25%
$3,070
Year 3+ · 7.25%
04 · Mortgage Coach TCA
Make the Decision Visible
Compare together. Choose the strategy. Share the TCA link. Payment. Cash to close. Cost over time.
Illustrative TCA example · $500,000 purchase · 20% down · $400,000 loan · 30-year fixed
Comparison
Option A
Option B
Option C
Example interest rate
6.500%
6.250%
6.125%
Discount points
$0
$4,000
$8,000
Monthly principal + interest
$2,528
$2,463
$2,430
Cash to close*
$108,000
$112,000
$116,000
5-year borrowing cost*
$134,140
$133,121
$134,614
Monthly fit
What feels comfortable?
Cash needed
What stays in reserve?
Time horizon
How long will you keep it?
Illustrative numbers, not current pricing or an actual Mortgage Coach report. Assumes $8,000 base closing costs and no MI. *Cash to close excludes escrows and prepaids. 5-year cost = interest + base closing costs + points. Source: Mortgage Coach Support Center.
05 · The local market
NJ Market Pulse: Monmouth vs. Ocean County
Closed residential sales, last 12 months. Knowing how sales are actually landing sharpens every offer you write.
60 and 240 months are not universal program rules. This is underwriting income, not a monthly cash distribution.
Community loan
“Heartbeat” explained
An alternative path when traditional income documentation is the obstacle. Income and employment are not stated on the application.
What still matters: credit and housing payment history, down payment or equity, verified assets, eligible property
A heartbeat alone does not qualify a buyer. Income-doc alternatives can carry higher rates or fees.
08 · The Buyer Pass
A Preapproval That Works Harder
Mortgage Coach advice. Housing Link delivery. Apple Wallet access. One link. A stronger financing story.
1
Compare in Mortgage Coach
Review payment, cash needed and 5-year cost.
2
Build the Housing Link
Bring together the preapproval, TCA and loan team.
3
Add the Buyer Pass to Apple Wallet
The buyer saves the pass before home shopping.
4
Show the pass at the open house
The agent scans to open the selected presentation.
09 · Your offer, supported
How We Help Get Your Offer Accepted
A stronger buyer. A clearer offer. A lender who makes the call. Bring us in before the offer goes in.
01
We call the listing agent
Explain the buyer's financing strength, confirm timing and address concerns.
02
Custom market insights
Review local sales, competition and sale-to-list trends with your agent.
03
Analysis with your client
Compare price, monthly payment, cash to close and reserves in Mortgage Coach.
04
Strengthen the buyer first
Review income, credit and assets. Pursue upfront underwriting when available.
05
Build the offer together
Align closing dates and seller priorities. Evaluate deposits and appraisal-gap capacity.
06
Stay involved through closing
Coordinate with the agent and client. Keep communication clear and follow through.
Offer terms and contingencies are reviewed with the buyer's agent and attorney. Financing remains subject to approval.
The market
What Moves Mortgage Rates?
Inflation up, bonds down, yields up, rates up. Softer jobs can ease rate pressure, if inflation cooperates.
Inflation
Prices + policy
Employment
Jobs + wages
Housing
Supply + demand
Geopolitics
Global uncertainty
All roads run through the 10-year Treasury to mortgage rates.
How we work
Less Busywork. More Time for People.
Automate the routine. Personalize the relationship. Our team reviews the output. People own the advice and decisions.
Meetings & follow-up
Fireflies captures notes and action items. We review and turn them into next steps.
Content & visibility
Turn our expertise into blogs, video scripts, social posts and partner education.
Knowledge & training
Ask Got Mortgages and NotebookLM help organize resources and build training.
Daily execution
Draft market updates and partner outreach. Connect workflows with Zapier and Buffer.
The business is growing.
+72%
Units & volume
Reported growth, Jan–Sept 2026
+56 BPS
Profitability
Reported improvement, Jan–Sept 2026
+104%
Units
Reported two-year growth, June 2026
+64%
Volume
Reported two-year growth, June 2026
AI helps us turn meetings into follow-up, expertise into content and resources into training. The tools support the work. The team drives the results.
Source: internal business figures shared by Abdel Khawatmi. Overall results; AI's individual contribution has not been measured. Reporting periods overlap.
Visibility trumps ability
Free Brand Audit
Get a clearer picture. A stronger strategy.
Your next opportunity starts with how people find you, recognize you and understand your value. Explore your brand with Got Mortgages, Powered by PRMG.
Your positioning
How you show up and stand out.
Your online presence
Your website, social media and SEO.
Your content strategy
What's working and what's not.
Your AI opportunities
Opportunities to work smarter, not harder.
Your next steps
A personalized action plan.
Got Mortgages AEO Site Checker
How well can AI find your website?
01
Enter your website
Check any page. No signup required.
02
Get your score
See a 0-100 score for AI search readiness.
03
Know what to fix
Review access, content and SEO issues.
Your expertise. Your free authority page.
Turn one market, niche or idea into a page built around what you want to be known for.
One AI-ready page: Built around your market, niche or idea.
A link you can share: Use it on social, in email and in direct outreach.
Leads sent to your phone: A lead form that texts responses to you.
Built for Google + AI: Sitemap, structured data and an AI-readable summary.
Starter marketing included: Social posts and a flyer from a one-time creative allowance.
Free value. No purchase required. Want help after launch? Your AI marketing department, available by text. Optional ongoing service, discussed separately.
Turn the session into deals. Start with one situation.
Today
Bring one situation
Pick one buyer, listing or stuck file
Write down the real obstacle in one sentence
Send it to us before your next showing
This week
Restructure your next concession
Ask where the seller credit does the most work
Compare buydown, points, costs and price side by side
Present options to the client, not just a rate
Before every offer
Run the deal before the deal
Consult, docs reviewed and budget set
Share a Buyer Pass with the listing agent
Write with a financing story, not a hope
Every month
Educate to create action
Share one market or rate update with your database
Explain what moves rates in plain language
Use GMU content to keep clients confident
Event FAQs
When and where was Deals & Drafts?
Tuesday, October 13, 2026 at 5:00 PM at Bakes Brewing, 1718 NJ-71, Belmar, NJ, hosted by Abdel Khawatmi of PRMG Got Mortgages and Steve Green of Green Label Title.
Can I watch the replay?
Yes. The full event replay is at the top of this page and on YouTube, followed by the event materials and a detailed recap checklist.
What did the session cover?
Title and closing readiness, the deal before the deal, how to structure seller concessions, the 2/1 buydown payment path, local Monmouth and Ocean County market data, traditional and alternative financing options, the Housing Link Buyer Pass, and what moves mortgage rates.
Are the payment examples real quotes?
No. The figures are illustrative, principal and interest only. Rates, payments and eligibility vary by borrower and program; every scenario is verified by a licensed loan officer.
Can I download the materials?
Yes. The Event Recap & Action Checklist, full presentation, infographic, sponsor showcase and free brand audit flyer are available to download on this page.
Who is hosting?
Got Mortgages, Powered by PRMG, together with Green Label Title, with support from our event sponsors.
Let's Turn Strategy Into Your Next Closing.
Your next buyer. Your next listing. Your next weird file. Your next negotiation.
Bring me the situation. Let's work through the options.
Abdel Khawatmi · GotMortgages@prmg.net · Got Mortgages, Powered by PRMG
We use strictly necessary storage to run this site. With your permission we also load optional tools, like our scheduling calendar and office maps, from third parties. See our Cookie Policy and Privacy Policy.